Insurance advice and broking

A fresh perspective on your insurance policies

HILEO advises businesses on their risks, structures their insurance programmes and negotiates cover. Specialist advice for AI infrastructure, technology businesses, and the finance and investment sector.

One point of contact, from risk analysis to claims

HILEO / The architect of your cover
Risks · Policies · CoverFrom financing to operations
AI infrastructure & data centresBusiness & technologyFinance & investmentExplore ↓

Our expertise

Understanding your business to structure your programme

Your business model, equipment and contractual commitments guide the choice of cover. HILEO works across three areas.

01 / INFRASTRUCTURE

AI infrastructure,
data centres and neoclouds

From financing to operations, a programme built around the risks you carry and your commitments to partners. Advice, programme structuring and negotiation with specialist insurers.
02 / BUSINESS AND TECHNOLOGY

Cyber insurance and financial lines for businesses

Protect your operations, data and directors’ liability. Advice on the risks to insure and the conditions under which a policy will respond.

Business and technology →
03 / FINANCE AND INVESTMENT

Asset managers, funds, fintechs and family offices

Professional indemnity, directors’ liability, cyber and crime. A programme structured around your operations, funds entrusted to you and your obligations.

Finance and investment →

The work behind the policy

Good advice comes down to the detail of cover

The declared activities, exclusions and claims conditions determine the scope of a policy. HILEO reviews and negotiates these terms in the context of your business.

Cover options and negotiation points are explained to you. Your point of contact knows your account.

01

Understand the risks and commitments

Activities, sites, equipment and obligations to clients, lenders and other partners.

02

Structure the programme

How policies work together, their limits and deductibles, and the risks you choose to retain.

03

Negotiate policy terms with insurers

Definitions, clauses and exclusions that need adapting, through to placement and ongoing policy management.

Reviews and advice

Take stock of your risks and policies

A programme built up over the years may leave risks uninsured or retain cover that is no longer needed. A policy review identifies the changes to make.

01Reviewing policies and how they work together
02Examining cover, limits and exclusions
03Written findings and recommendations

For businesses and financial institutions, the engagement can also begin with a review of risks and documented prevention measures.

Client matters

Our work with clients

Anonymised matters and findings from our work with clients.

02
Cyber · €100,000 claimed

The uninsured claim

A cyberattack stops campaigns for hundreds of advertisers. The company discovers that it is insured for its own losses, but not for claims from its clients.

Read the case +

An employee’s account is hacked. The attacker takes control of the master advertising account and launches fraudulent campaigns. Accounts are blocked, campaigns stop and an advertiser claims €100,000 for lost revenue and reputational damage. The limitation only becomes apparent when the claim is made.

03
Directors · Exclusion

Insured on page one. Excluded two clauses later

The directors are named as insureds. Yet their personal liability as directors is not covered.

Read the case +

The exclusion extends to mismanagement claims, creditor actions in the event of insufficient assets, and employment disputes. The directors are named in the policy, but the circumstances that expose their personal assets remain outside its cover.

04
International · 1/3 of revenue

A condition that undermines the cover

Cyber cover appears to be in place. Yet a territorial condition makes it ineffective for almost a third of the company’s business.

Read the case +

The company generates almost a third of its revenue in North America. The policy makes cover conditional on revenue generated in the United States. The condition was in the policy schedule, but had never been checked against the actual geographical breakdown of the business.

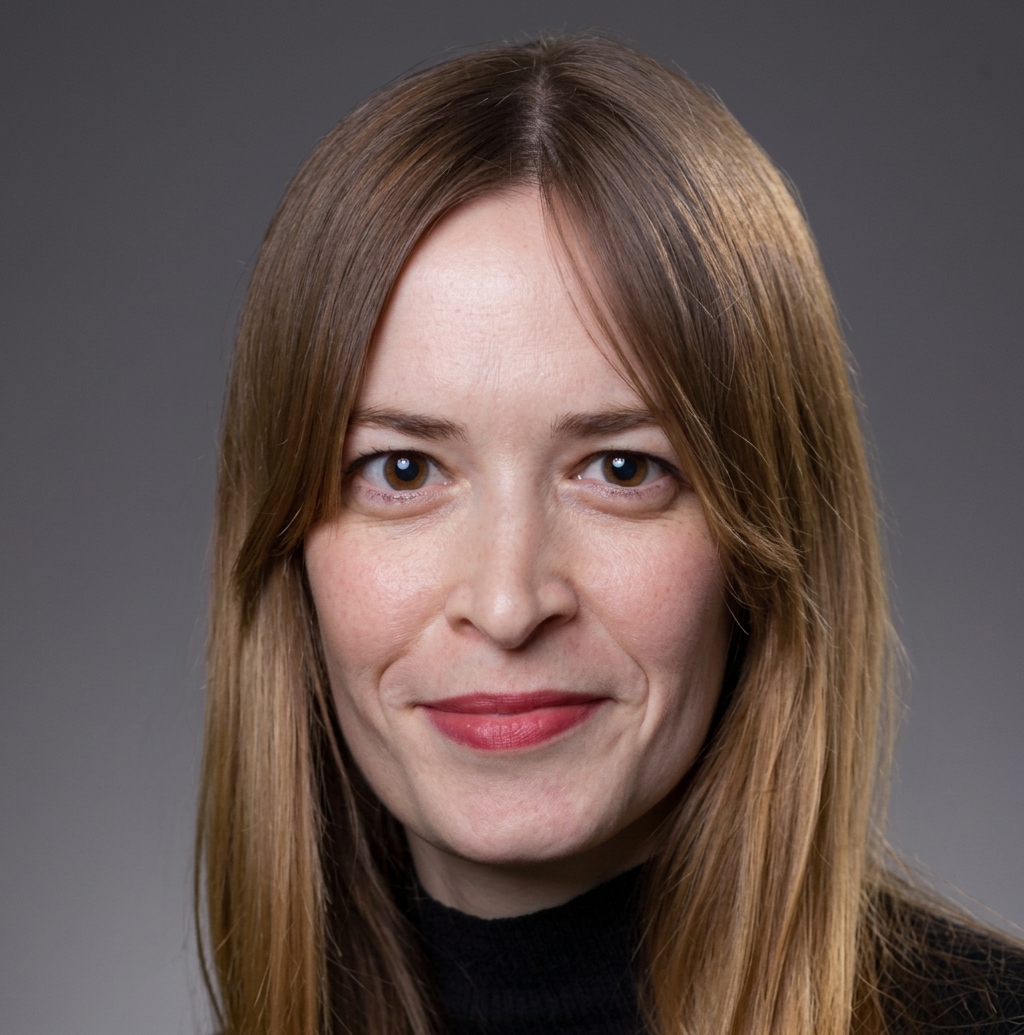
Iris Monderer, founder of HILEO
Iris Monderer · Founder of HILEO

About HILEO

You deal directly with me, from review to claim

I spent many years placing international programmes and specialist risks with global insurance brokers.

I founded HILEO to bring that expertise to businesses seeking the same standard of advice as large groups. Businesses whose programmes have grown alongside their activities, in response to client requests and lenders’ requirements, without a full review of the insurance arrangements.

I personally carry out each review and remain your point of contact through to claims management.

Iris MondererFounder

Frequently asked questions

Before we work together

Advice, reviews, placement and ongoing support: answers to your first questions.

Discuss it with Iris

Getting started

What does HILEO do beyond finding an insurance policy?

HILEO analyses your business and commitments, advises on the programme structure, then negotiates cover with insurers. The work addresses definitions, exclusions, limits and claims conditions. The same person follows your account through placement and the life of your policies.

Can HILEO help if I already have a broker?

Yes. The engagement can begin with a review of your risks or existing policies. The scope is agreed with you. The review does not trigger any cancellation or require you to change broker.

What documents should I prepare for the first discussion?

An overview of your business and needs is enough to get started. Depending on the matter, HILEO will then request insurance policies, information on sites and equipment, or commitments to clients, lenders and other partners. A confidentiality agreement can be signed before documents are shared.

Reviews and advice

What does an insurance programme review cover?

HILEO reviews your policies and how they work together: declared activities, insured persons and entities, limits, deductibles, exclusions and policy conditions. Gaps between the programme and your business or commitments are identified. You receive written findings and recommendations on the cover to retain, strengthen or renegotiate.

How are security measures reviewed?

HILEO carries out a document-based review of the procedures and controls described by the business: access management, payment authorisation, permissions and prevention measures, as relevant. The current scope does not include technical testing, penetration testing or site inspections.

Does a review always have to come before arranging cover?

No. For a specific policy, HILEO can carry out a targeted market exercise once the need has been defined. A new programme or a significant change in activity requires broader advice and structuring. HILEO agrees the approach and timetable with you.

Placement and ongoing support

How does HILEO approach insurers?

After analysing the risks and defining the cover required, HILEO prepares the submission and approaches suitable insurers. Proposals are assessed on premium, clauses, exclusions and claims conditions. Negotiated points and the decisions to be made are explained to you.

How is a change of policies organised?

If a change or replacement is agreed, HILEO reviews notice periods, inception dates and the terms of the new policies before any cancellation. The transition takes account of claims reporting provisions and the continuity of cover sought.

Who manages the programme after placement?

Iris Monderer remains your point of contact for programme changes, renewals and claims support. Changes to your activities, sites or contractual commitments are reviewed to determine the adjustments needed.

Your insurance programme

Discuss your needs

A programme to structure, cover to negotiate or policies to review. The first discussion helps define the work required.